How to Start a Small Business in 10 Practical Steps
Written by : Ilias Hajjoub | Reading time : 10 min | 30 August 2026
Starting a small business is easier when you stop treating it as one enormous decision.
You do not need the perfect brand, a complex business plan or an expensive technology stack before you begin. You need to know who you want to serve, what problem you can solve for them, whether they are willing to pay, and whether the numbers can work. Everything else should be built around those answers.
That matters even more in 2026. AI, automation, cloud software and digital platforms can help a small team research markets, build products, reach customers and run operations with far fewer resources than before. But technology does not replace the fundamentals of a viable business. It simply gives founders more leverage once those fundamentals are right.
This guide explains how to start a small business in 10 practical steps, from validating your idea and calculating startup costs to registering the company, finding customers, using AI intelligently and measuring what happens after launch.
The goal is not simply to get your business open. It is to build one that has a credible path from idea to first customer and from first customer to sustainable growth.
Content Table
- How do you start a small business?
- Step 1: Validate Your Business Idea Before You Build It
- Step 2: Define How the Business Will Actually Make Money
- Step 3: Write a Business Plan You Will Actually Use
- Step 4: Calculate Your Startup Costs and Decide How to Fund the Business
- Step 5: Choose Your Business Name, Location and Legal Structure
- Step 6: Register the Business and Handle Compliance
- Step 7: Set Up Banking, Accounting and Financial Controls
- Step 8: Build a Lean Technology and AI Stack
- Step 9: Build Your Brand, Website and Customer Acquisition System
- Step 10: Launch Small, Measure What Happens and Improve
- Starting a Small Business in 2026: What Has Changed?
- The Most Common Mistakes When Starting a Small Business
- How Much Money Do You Need to Start a Small Business?
- FAQ
How do you start a small business?
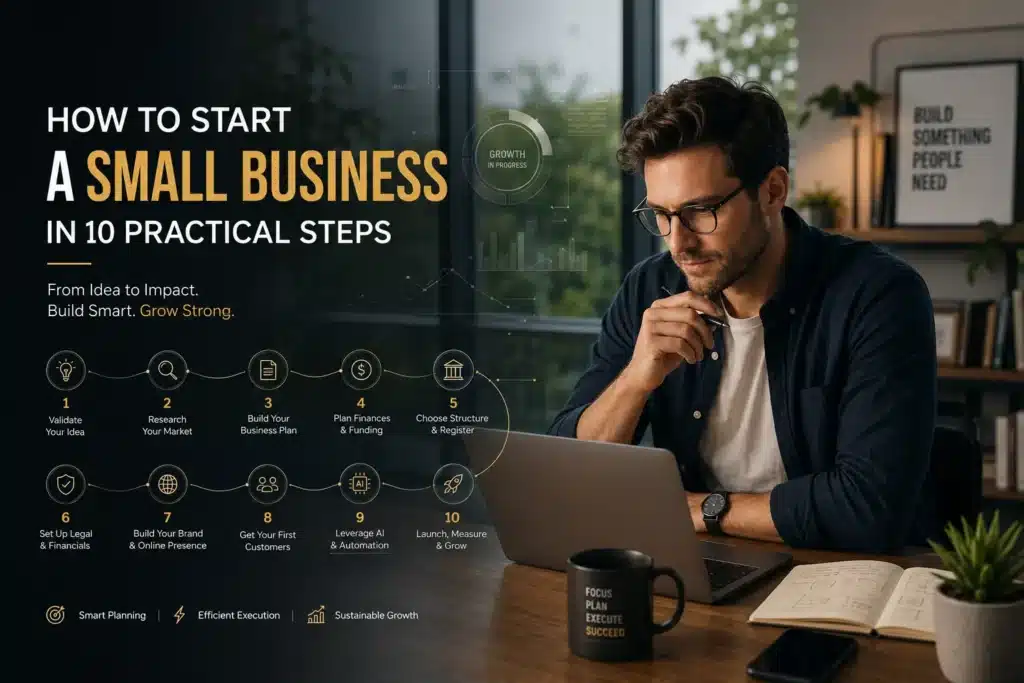
To start a small business, you need to validate that customers want what you plan to sell, define how the business will make money, create a business plan, calculate your startup costs, choose the right legal setup, register and organize your finances, build the necessary operating systems, create a customer acquisition strategy, and launch with measurable goals.
The process can be summarized in ten stages:
Step | What you need to accomplish |
1 | Validate the business idea and real customer demand |
2 | Define the business model and economics |
3 | Write a practical business plan |
4 | Calculate startup costs and choose how to fund the business |
5 | Choose your name, location and business structure |
6 | Register the business and handle legal requirements |
7 | Set up banking, accounting and financial controls |
8 | Build your technology, AI and operating stack |
9 | Build the brand, website, marketing and sales system |
10 | Launch, measure, learn and improve |
This sequence deliberately puts customers and economics before paperwork. The SBA similarly begins its planning guidance with market research, competitive analysis, business planning, startup costs and funding before moving into registration, tax IDs, licenses, banking and insurance.
Important: This guide is international in scope. Company structures, tax registrations, licenses, employment rules and reporting requirements vary significantly by country, state, province and municipality. References to structures such as LLCs or tax identifiers such as EINs are U.S. examples, not universal requirements.
Step 1: Validate Your Business Idea Before You Build It
A business idea is an assumption until someone wants to pay for it.
That makes market validation the first serious step in starting a small business.
You need answers to several questions: Who exactly is the customer? What problem are they trying to solve? How are they solving it today? What do existing alternatives cost? Why would someone choose you instead? And, most importantly, is there evidence of willingness to pay?
The SBA recommends examining demand, market size, location, market saturation, customer characteristics and existing pricing. It also distinguishes between secondary research, such as industry and demographic data, and direct research through surveys, interviews, questionnaires and focus groups.
Competitor research should go beyond identifying who ranks first on Google. Study competing offers, reviews, pricing, positioning, complaints, delivery times, customer experience and the questions customers repeatedly ask. Stripe’s startup guidance similarly recommends examining competitors’ strengths and weaknesses, talking directly with potential customers and testing a minimum viable product rather than assuming an idea will succeed.
Validate the problem before perfecting the solution
Suppose you want to launch an AI automation consultancy for restaurants.
Do not begin by spending weeks designing a logo and building a complex website.
First determine whether restaurant owners have costly repetitive processes that they actually want solved. Perhaps reservations are being missed on WhatsApp. Maybe staff repeatedly answer the same questions. Maybe review management consumes hours each week.
Those are problems.
“Restaurants should use AI” is merely a hypothesis.
Your early objective is to find the intersection between a real problem, a reachable customer and an offer someone is willing to pay for.
That logic applies whether you are opening a bakery, starting a consultancy, building a SaaS product, launching an e-commerce store or creating a local cleaning company.
Turn Your Business Idea Into a Growth System
Step 2: Define How the Business Will Actually Make Money
Once demand looks credible, turn the idea into a business model.
A business model explains who pays you, what they pay for, how much they pay, what it costs you to deliver, and how the customer reaches you.
This is where many exciting ideas become either commercially interesting or financially impossible.
For a new business, the essential economics are not complicated:
Metric | What it tells you |
Revenue | How much money the business generates |
Variable cost | What each additional sale costs to fulfil |
Gross margin | What remains after direct delivery costs |
Fixed costs | Expenses that continue regardless of sales |
Break-even point | How much you must sell before covering costs |
Customer acquisition cost | What it costs to gain a customer |
Average order or contract value | The typical value of a sale |
Repeat purchase or retention | Whether customers come back |
Cash runway | How long available cash can support operations |
A simple example explains why this matters.
Selling a product for $100 does not mean you make $100. If the product costs $35, fulfilment costs $10, payment fees cost $3 and acquiring the customer costs $25, much less remains to cover payroll, software, rent, taxes and profit.
Before choosing colors for the brand, understand the economics behind the sale.
This becomes even more important for businesses that rely on paid acquisition. A company can generate impressive revenue while destroying cash if acquiring and serving each customer costs too much.
Step 3: Write a Business Plan You Will Actually Use
A business plan should force better decisions, not simply produce a long document.
The SBA describes a business plan as a roadmap for structuring, operating and growing a company and recognizes both traditional and lean startup formats. A detailed traditional plan is usually more appropriate when seeking bank financing or external investment. A simpler business can often begin with a lean plan that captures the fundamental economics and strategy on a much smaller document.
At minimum, your plan should make the following clear:
Customer: Who are you serving?
Problem: What are they trying to solve?
Offer: What exactly will you sell?
Positioning: Why should customers choose you?
Revenue model: How will you get paid?
Costs: What will it cost to launch and operate?
Acquisition: How will customers discover the business?
Operations: What has to happen after someone buys?
Targets: What needs to be true in three, six and twelve months?
Risks: What could invalidate the plan?
Treat the financial section as a model, not a prophecy. Forecasts will change. Their purpose is to expose assumptions early enough to challenge them.
NerdWallet similarly recommends treating projections and cash-flow expectations as living parts of the business plan rather than fixed numbers that are written once and forgotten.
Step 4: Calculate Your Startup Costs and Decide How to Fund the Business
There is no useful universal answer to “How much does it cost to start a small business?”
A solo consultant working remotely and a restaurant opening a physical location are both small businesses, but their capital requirements are fundamentally different.
Instead of relying on an online average, calculate your own startup requirement.
Start with one-time launch costs, such as equipment, initial inventory, deposits, incorporation expenses, branding, or website development. Then estimate recurring fixed costs, including rent, salaries, subscriptions, accounting, and insurance. Add the variable cost of producing or delivering each sale and enough working capital to survive the period before revenue becomes predictable.
The SBA specifically recommends calculating startup costs before launch because the exercise helps estimate profitability, conduct break-even analysis, prepare financing requests, and identify the capital needed to operate.
How should you fund a new small business?
Funding generally comes from some combination of founder capital, early customer revenue, loans, grants, crowdfunding, or outside investors.
The right method depends on what you are building.
A consulting business that can become profitable after its first few clients may have little reason to surrender equity. A manufacturing company requiring expensive machinery faces a different calculation. A scalable technology startup pursuing rapid international growth may have another financing strategy entirely.
Capital also has a cost, even when that cost is not immediately visible.
Federal Reserve Small Business Credit Survey data published in 2026 found that 60% of surveyed employer firms had applied for financing during the previous 12 months. Among applicants, 42% received the full amount requested, while 22% received none. The research also found substantially more reports of unexpectedly high borrowing costs among borrowers using online lenders than among borrowers using banks.
The lesson for a new founder is simple: build the business around realistic access to capital, not capital you assume will arrive later.
Step 5: Choose Your Business Name, Location and Legal Structure
Now the company needs an identity and legal form.
A strong business name should be distinctive, pronounceable, memorable, and usable where customers will encounter it. Before committing to it, check applicable company registries, trademarks, domain availability, and major social platforms.
Do this before investing heavily in signage, packaging, or brand assets.
Location deserves similar attention. For a physical business, location can influence rent, foot traffic, labor availability, logistics, licenses, taxes, and zoning. For an online business, the founder’s legal residence and the jurisdictions where the company operates or sells can still create regulatory and tax obligations.
Then choose the appropriate legal structure.
There is no universally “best” business structure. The right form depends on ownership, liability exposure, taxation, administration, investment plans, and local law. In the United States, for example, possible structures include sole proprietorships, partnerships, LLCs, and corporations; other countries use entirely different legal forms.
Even the formal definition of a “small business” is not universal. The SBA’s U.S. size standards vary by industry and are generally expressed through annual receipts or employee counts rather than one blanket headcount threshold.
If the choice has meaningful legal or tax consequences, use a qualified local accountant or business lawyer rather than copying another founder’s structure.
Step 6: Register the Business and Handle Compliance
Once the structure has been chosen, turn the project into a legally operational company.
Depending on jurisdiction and industry, that may involve company registration, tax identification, sector licenses, municipal permits, employment registrations, insurance, data protection requirements, health or safety approvals, intellectual-property filings and other obligations.
A home-based consultant will not face the same requirements as a medical clinic, restaurant, construction contractor, financial service or food manufacturer.
That is why “register your company” should never be treated as a single universal instruction.
In the United States, the SBA’s launch sequence includes choosing the structure and name, registering the business, obtaining applicable federal and state tax IDs, applying for licenses and permits, opening a business bank account and obtaining appropriate insurance.
For businesses operating elsewhere, use the equivalent national and local authorities.
And do this before accepting business risks that require those permissions or protections. Market research can often happen long before formal incorporation; regulated commercial activity cannot necessarily do the same.
Step 7: Set Up Banking, Accounting and Financial Controls
Your first financial system does not need to be sophisticated. It needs to be clean.
Separate business and personal transactions as early as practical and legally appropriate. Use proper bookkeeping, decide how invoices and payments will be handled, understand when taxes become payable and establish a routine for reviewing cash flow.
NerdWallet identifies separating personal and business finances as basic bookkeeping hygiene and recommends using dedicated business banking and accounting systems to make financial records easier to manage.
One concept deserves particular attention:
Profit and cash are not the same thing.
A business can be profitable on paper and still run out of cash because customers pay late, inventory is purchased upfront, debt has to be serviced or growth consumes working capital.
From the beginning, know how much cash is available, how much enters the company, how much leaves, what is already committed and what the next several months are likely to require.
Financial visibility is not something to install once the company becomes “serious.”
It is one of the things that makes it serious.
Step 8: Build a Lean Technology and AI Stack
Starting a small business in 2026 is increasingly also an exercise in systems design.
You may need a professional domain and email, cloud storage, accounting software, a payment system, CRM, project or task management, website analytics, password management, backups and basic cybersecurity controls.
But more software does not automatically create a better company.
Start with the systems required to execute your actual customer journey. Add tools when they eliminate a real constraint.
Where should a new small business use AI?
AI adoption among newer businesses is accelerating sharply. JPMorganChase Institute transaction data found that businesses entering its sample in 2025 reached a 10% AI-adoption level within roughly six months; the equivalent 2019 cohort took more than six years. The same research found that 6.5% of the 2025 cohort had already paid for AI services in its first month of operation.
That does not mean every startup needs an elaborate AI strategy.
It means founders can now use inexpensive technology to perform work that once required much larger teams.
Federal Reserve survey results released in 2026 found that writing and marketing were the most common reported AI use cases among AI-using small firms, followed by individual productivity and planning or analysis. Seventy-one percent reported increased productivity, while 31% reported higher sales.
A broader 2026 UK government study makes the nuance even clearer: 56% of AI-using businesses reported increased employee productivity, but 77% said they had not yet experienced a change in revenue. Most also retained human oversight over AI outputs.
That is a useful principle for a new company:
Use AI first where it saves time, increases consistency or improves information. Do not assume automation automatically creates demand or revenue.
AI can help with research, proposal preparation, support triage, lead qualification, content workflows, administrative processes, reporting and data analysis. More advanced businesses can eventually connect these functions through AI assistants, automation workflows, CRM systems and proprietary data. Kifcom’s own AI practice follows the same progression: identify valuable use cases, connect them to measurable business objectives, begin with focused implementations and scale after results are proven.
Step 9: Build Your Brand, Website and Customer Acquisition System
A company is ready to sell when people can understand what it offers, trust it enough to engage and take the next step without friction.
That requires more than a logo.
Your positioning should answer three questions quickly:
Who is this for?
What valuable outcome do we provide?
Why should someone choose us rather than an alternative?
From there, build the minimum digital presence necessary for your market.
For many businesses, the website becomes the central asset: the place where customers understand the offer, evaluate credibility, compare options, contact the company, request a quote, book an appointment or purchase.
A strong small-business website should therefore be designed as an acquisition system rather than an online brochure. Kifcom’s web-development approach reflects that distinction by connecting design with SEO architecture, user experience, performance and conversion rather than treating the website purely as a visual project.
Choose marketing channels based on buyer behavior
Do not launch Instagram, LinkedIn, TikTok, YouTube, email campaigns, Google Ads and an SEO program simultaneously simply because those channels exist.
Ask where your customer searches, evaluates and makes decisions.
A local emergency service may depend heavily on Google Search and local visibility. A B2B consultancy may gain more from LinkedIn, referrals, outbound sales and expert content. An e-commerce brand might require a combination of search, social advertising, creators, email and retention. A SaaS company may rely on content, product-led acquisition, partnerships or sales teams.
Your marketing plan needs a customer acquisition hypothesis:
Audience → message → channel → offer → conversion → follow-up → measurement.
Stripe similarly recommends defining the target audience, marketing objectives, channels, brand messaging, sales process and measurement before treating marketing as a collection of promotional activities.
At launch, one channel that produces qualified customers is worth more than six channels producing activity.
Step 10: Launch Small, Measure What Happens and Improve
Launch is not the end of business creation.
It is the moment reality starts correcting the plan.
Instead of waiting for every detail to become perfect, launch when the product or service is credible, legal, safe and capable of producing the promised customer outcome.
Then pay close attention.
Revenue is important, but early-stage businesses need to understand why revenue is or is not happening.
Metric | Question it answers |
Qualified leads | Are the right people showing interest? |
Conversion rate | Does the offer persuade them to buy? |
Customer acquisition cost | Can you acquire customers economically? |
Gross margin | Is each sale financially healthy? |
Sales cycle | How long does a customer take to decide? |
Repeat purchase / retention | Does value continue after the first sale? |
Refunds or cancellations | Are expectations and delivery aligned? |
Cash flow | Can the company continue operating? |
Customer feedback | What should be improved next? |
Stripe’s startup guidance explicitly recommends testing systems before launch, implementing analytics, planning post-launch operations and continually evaluating performance rather than treating launch day as the finish line.
Your early goal is not to look large.
It is to learn quickly enough to become good.
Starting a Small Business in 2026: What Has Changed?
The fundamental principles of entrepreneurship have not changed. Customers still need a reason to buy. Revenue still has to exceed costs eventually. Cash flow still matters. Trust still matters.
What has changed is the infrastructure available to a very small company.
Small teams have access to capabilities that once required departments
Website development, CRM, payment processing, analytics, video production, customer support, workflow automation, and sophisticated AI tools are increasingly accessible without enterprise-level budgets.
JPMorgan Chase Institute’s 2026 research suggests the competitive question may consequently move from whether businesses adopt AI to how effectively they integrate it.
That is a significant shift.
Technology is lowering the cost of execution. It is not removing the need for strategy.
AI makes average execution easier, which makes differentiation more valuable
If every competitor can generate articles, advertisements, presentations, emails and product descriptions in seconds, producing more material stops being much of an advantage.
Understanding customers better becomes more valuable.
Original data becomes more valuable.
A distinctive brand becomes more valuable.
A better product becomes more valuable.
Exceptional service becomes more valuable.
And human judgment becomes more valuable precisely because automation is becoming cheaper.
This is a strategic implication of rapidly widening access to AI: technology can reduce the cost of execution, but it cannot decide why customers should care about your business. OECD research likewise emphasizes that effective SME AI adoption depends not only on access to technology but also on digital maturity, skills, data, infrastructure and finance.
The Most Common Mistakes When Starting a Small Business
Mistake | Better approach |
Registering and building before validating demand | Research customers and test the offer first |
Copying a competitor’s price | Model your own costs, margin and customer value |
Spending heavily on branding before sales | Establish positioning first and scale the identity with the business |
Choosing every marketing channel | Concentrate on the channels where buying intent actually exists |
Mixing personal and business finances | Establish clean financial separation and bookkeeping |
Buying too much software | Build the minimum operating stack required |
Automating everything with AI | Automate repetitive work while retaining human oversight where judgment matters |
Tracking followers instead of customers | Measure leads, conversions, margin, acquisition cost and retention |
Assuming funding will arrive | Build forecasts around capital you realistically control or can access |
Waiting for perfection | Launch a credible version, collect evidence and improve |
How Much Money Do You Need to Start a Small Business?
There is no single amount.
A skill-based service business can sometimes begin with very little capital because the founder already owns the primary productive asset: expertise. Businesses involving inventory, premises, regulated equipment, manufacturing, employees or significant product development can require substantially more.
The useful number is therefore not an online “average startup cost.”
It is:
Launch costs + operating costs until sustainable cash flow + a margin for uncertainty.
Calculate that figure for the business you are actually building. The SBA recommends doing this before launch so founders can estimate profitability, break-even requirements and financing needs.
FAQ
How do I start a small business?
Start by identifying and validating a real customer problem. Define your offer and business model, create a practical business plan, calculate startup costs, select the appropriate legal structure, register the business, establish its financial and digital infrastructure, acquire your first customers and continuously measure performance.
How much does it cost to start a small business?
There is no standard startup cost. Service and digital businesses can sometimes launch with relatively little capital, while restaurants, retail stores, manufacturing companies, and regulated businesses can require significant investment. Calculate one-time expenses, recurring operating costs and sufficient working capital for your particular model before launching.
Can you start a business with no money?
Certain service, freelance and digital business models can begin with very little upfront capital, especially when the founder already has the necessary equipment and skills. A truly zero-cost business is less common because registration, software, payment processing, insurance, marketing or operating expenses may still arise.
The better question is: what is the least capital required to test whether customers will pay?
Do I need a business plan?
You should have a business plan, but it does not always need to be long. A lean operating plan may be enough for a self-funded small business. Banks and investors will generally require more extensive financial, market and operational information.
Should I build a website before starting my business?
You can use a simple landing page during validation, but your full website should follow a clear understanding of the offer, customer and positioning. For most modern businesses, an owned web presence becomes important for credibility, discovery, lead generation or transactions once the company is preparing to launch.
What is the biggest mistake when starting a small business?
One of the most expensive mistakes is building too much before proving demand. Founders can spend months on branding, products, technology and infrastructure before discovering that the target customer, offer, pricing or acquisition strategy does not work.
Validate first. Build second. Scale what works.

Ilias Hajjoub
Ilias is the Head of SEM and Digital Marketing at Kifcom 360. Passionate about artificial intelligence, SEO and performance marketing, he designs data-driven and automation-powered campaigns to maximize ROI. From acquisition strategy and conversion funnel optimization to continuous monitoring of emerging technologies, he constantly pushes the boundaries of digital marketing performance